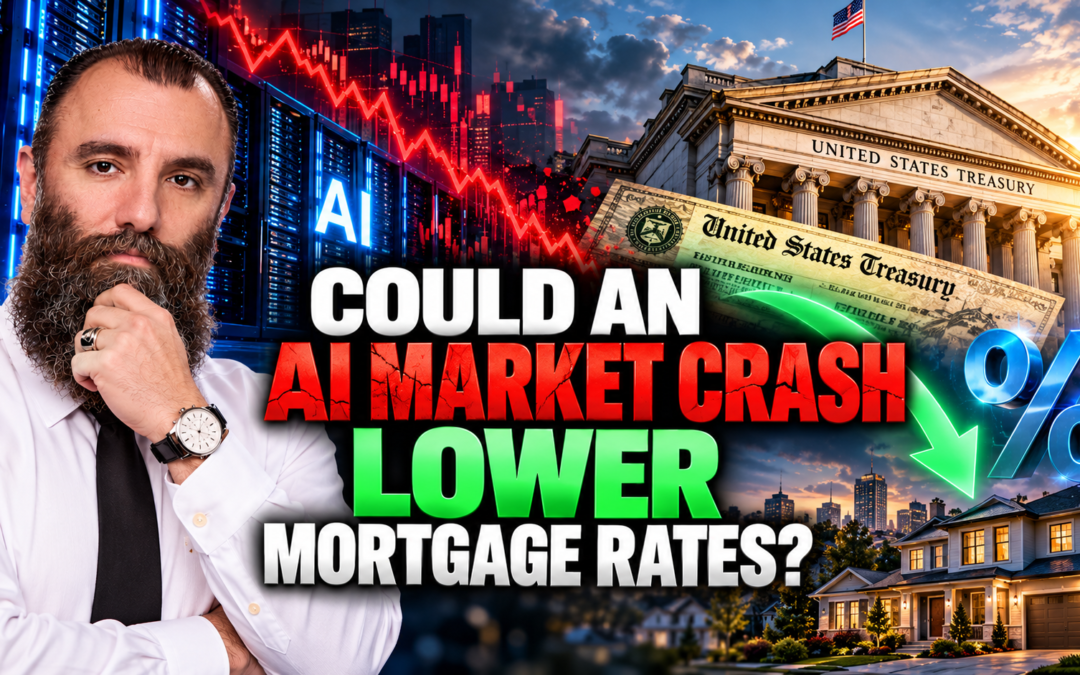
Could an AI Crash Actually Lower Mortgage Rates?
How the artificial intelligence revolution could reshape the Treasury bond market, inflation, and the cost of buying a home.
Economic Analysis | October 2026
What if one of the biggest forces influencing your next mortgage rate isn't the Federal Reserve, but artificial intelligence?
And what if the success of AI companies could keep borrowing costs elevated, while an AI stock market crash could potentially bring mortgage rates down?
It sounds counterintuitive. But when you understand how the 10-year U.S. Treasury market works, the relationship becomes surprisingly logical.
The answer is not as simple as saying an AI boom means higher rates and an AI crash means lower rates. The real outcome depends on economic growth, inflation expectations, demand for capital, and investor behavior.
1. The Hidden Connection Between Treasury Bonds and Mortgage Rates
Many Americans believe the Federal Reserve directly controls mortgage rates. That's not quite how the market works.
The Fed sets a target range for the federal funds rate, which influences short-term interest rates. But 30-year fixed mortgages are priced in longer-term financial markets.
One of the most important benchmarks is the 10-year U.S. Treasury yield.
Although a mortgage may last 30 years, homeowners often sell, move, or refinance long before the loan reaches maturity. This helps explain why the 10-year Treasury is an important reference point.
How Treasury demand affects yields
Bond prices and yields move in opposite directions. When investors purchase existing Treasury securities, increased demand can drive their prices higher. Because the securities' promised payments are fixed, their yields decline as prices rise.
Mortgage-backed securities often respond to similar economic forces, so mortgage rates generally follow Treasury yields directionally.
Mortgage Rate ≈ 10-Year Treasury Yield + Mortgage Spread
The mortgage spread accounts for additional risks, servicing costs, origination expenses, and lender margins. It can change considerably during periods of market uncertainty.
2. The AI Investment Boom: Why Success Could Keep Rates High
Artificial intelligence is no longer simply about software applications or chatbots. It has become a massive infrastructure story.
Companies are investing heavily in data centers, advanced semiconductors, electricity, cooling infrastructure, construction, and computing equipment.
According to research published by the Federal Reserve Bank of Minneapolis, projected capital spending by five major AI infrastructure investors could approach $1 trillion in 2027, compared with approximately $200 billion in 2024.
That 2027 figure is a projection, not spending that has already occurred.
Why does that matter for mortgage rates?
Because investment requires capital. When businesses compete for financing, workers, construction materials, and electricity, the resulting demand can put upward pressure on real interest rates.
Strong economic growth can also cause investors to expect higher interest rates in the future, which may push longer-term Treasury yields higher.
3. Could AI Create Economic Growth Without Inflation?
This is where the story becomes even more interesting.
Imagine artificial intelligence allowing businesses to produce substantially more goods and services using fewer resources per unit of output.
AI could improve logistics, automate administrative processes, accelerate engineering, reduce errors, and help companies operate more efficiently.
Economists call this productivity growth.
If the economy becomes capable of producing more without a comparable increase in demand for scarce resources, inflationary pressure can ease.
Investment-Driven AI Boom
Strong demand for capital, electricity, equipment, and construction supports growth but may keep real interest rates high.
Potentially higher Treasury yieldsProductivity-Driven AI Boom
Businesses increase output and reduce unit production costs, potentially moderating inflation.
Potentially lower inflation pressureBut there's an important distinction: lower inflation does not guarantee lower interest rates.
A highly productive economy may also generate excellent investment opportunities, increasing demand for capital and keeping inflation-adjusted interest rates relatively high.
Both effects could occur simultaneously.
Another misconception is that soaring AI stock prices automatically inject equivalent amounts of new money into the economy. Higher stock valuations represent increased asset values, not necessarily new money creation.
Those valuations may stimulate consumption through wealth effects or support financing for new investments, but the transmission to inflation and interest rates is indirect.
4. What Happens If the AI Boom Collapses?
Now consider the opposite scenario.
Suppose investors begin questioning whether AI companies will generate enough profits to justify their enormous valuations and infrastructure spending.
Technology stocks could decline sharply. Some investment projects might be postponed. Businesses could reduce spending, and economic growth expectations could weaken.
Investors might respond by moving capital out of riskier assets and into securities they perceive as safer.
One traditional destination during financial uncertainty is the U.S. Treasury market.
As demand for Treasuries rises, bond prices may increase and yields may decline.
If the downturn also causes investors to expect slower growth and future Federal Reserve rate cuts, longer-term yields could face additional downward pressure.
This is the economic mechanism behind the hypothesis that an AI market crash could help lower mortgage rates.
But There's a Catch
Financial stress can cause mortgage spreads to widen. Mortgage investors may demand additional compensation for liquidity, prepayment uncertainty, or credit risk.
That means Treasury yields could decline without mortgage rates falling by the same amount.
A severe economic downturn could also create job losses, tighter lending conditions, and reduced household confidence.
5. Four Possible Economic Outcomes
| AI Scenario | Treasury Yields | Mortgage Rates |
|---|---|---|
| Major AI investment boom | Upward pressure | May remain elevated |
| Productivity gains reduce inflation | Mixed; could decline | Could decline |
| AI crash triggers flight to safety | Likely downward pressure | Could fall |
| AI crash creates financial stress | Uncertain | May remain elevated or volatile |
These scenarios are directional illustrations, not predictions or guarantees.
6. Interactive Mortgage Payment Calculator
What would a decline in mortgage rates actually mean for a homebuyer?
Use this calculator to explore how changing interest rates affect the monthly principal and interest payment on a 30-year fixed mortgage.
$600,000
Illustrative 30-year fixed-rate mortgage. Excludes taxes, insurance, HOA fees, mortgage insurance, and closing costs. The example rates are not forecasts or lender quotes.
On a $600,000 mortgage, reducing the interest rate from 7.25% to 5.25% lowers the monthly principal and interest payment by approximately $780.
That's more than $9,000 per year in potential cash-flow savings.
Of course, lower mortgage rates may also increase buyer demand and competition, potentially pushing home prices higher.
7. The Four Economic Indicators Worth Watching
10-Year Treasury Yield
A key benchmark for long-term borrowing costs and mortgage pricing.
Inflation and Productivity
Is AI increasing productive capacity, or primarily increasing demand and production costs?
AI Corporate Performance
Are AI companies producing enough revenue and profit to justify their capital investments?
Mortgage Spreads
Are mortgage rates following Treasury yields, or are investors demanding additional compensation?
8. Frequently Asked Questions
Does the Federal Reserve directly control mortgage rates?
No. The Fed influences short-term interest rates and broader financial conditions. Long-term mortgage rates are determined in capital markets and reflect expectations for inflation, growth, interest rates, and mortgage risk.
Why do Treasury bond prices and yields move in opposite directions?
Existing fixed-income securities promise fixed payments. When investors pay a higher price for those payments, the return relative to the purchase price declines.
Would an AI market crash guarantee lower mortgage rates?
No. Investors might move into Treasuries, reducing yields, but mortgage spreads could widen during financial stress. Other economic factors also influence rates.
Can AI reduce inflation without lowering mortgage rates?
Yes. Productivity gains can moderate inflation while strong investment demand and economic growth keep real interest rates elevated.
Should buyers wait for an AI market correction?
Attempting to time the housing market around an AI stock-market correction is speculative. Buyers should consider affordability, employment stability, available inventory, financing options, and long-term objectives.
9. The Bottom Line: The Next Major Mortgage Rate Shift May Begin in a Data Center
Artificial intelligence could become one of the most consequential economic forces of our generation.
But its impact on interest rates is not straightforward.
An AI investment boom could increase demand for capital and support higher Treasury yields.
An AI productivity revolution could ease inflationary pressure and potentially help bring borrowing costs down.
An AI stock-market crash could trigger a flight to safety into Treasury securities, reducing yields and potentially lowering mortgage rates.
And all three forces could interact in unexpected ways.
For homebuyers, sellers, and real estate investors, understanding these connections can provide a clearer perspective on the forces shaping housing affordability.
The objective isn't to predict the future with certainty. It's to understand the economic mechanisms well enough to make informed decisions.
Research and Sources
- Federal Reserve Bank of Minneapolis — How AI Is Influencing Interest Rates
- Federal Reserve Bank of St. Louis — What Determines Mortgage Rates?
- Fannie Mae — What Determines the Rate on a 30-Year Mortgage?
- Federal Reserve Bank of New York — Artificial Intelligence and Monetary Policy
- Freddie Mac — Primary Mortgage Market Survey
Disclaimer: This article is for educational and informational purposes only and does not constitute personalized financial, mortgage, investment, or legal advice. Economic scenarios are hypothetical and outcomes are not guaranteed.